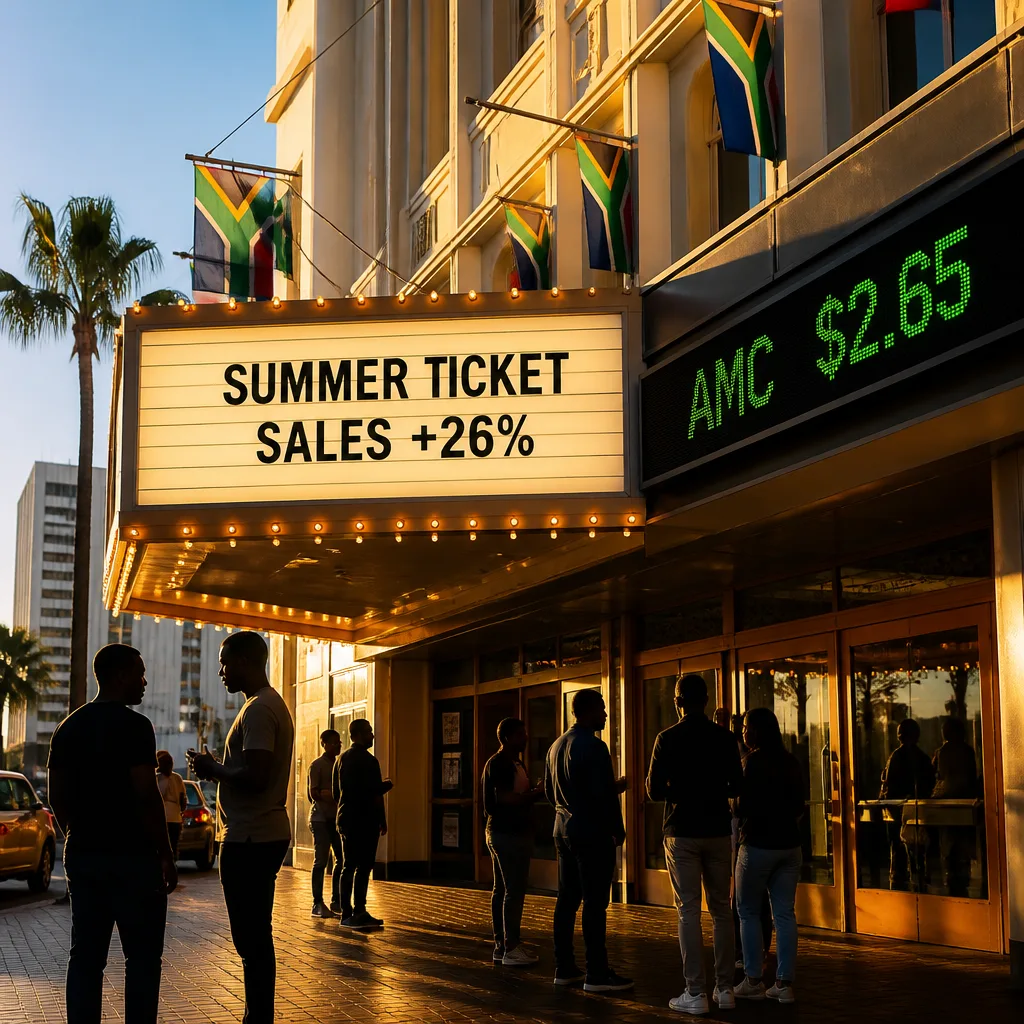
AMC Entertainment — the world’s largest movie-theatre chain that became a household name during the 2021 meme-stock frenzy — is once again drawing investor attention, but this time for very different reasons. After surging more than 1,100% in 2021 to above $600 a share, the company’s stock has since suffered steep declines and was recently trading at roughly $2.65–$2.67 per share, firmly back in penny-stock territory.
From meme mania to penny-stock pricing
Since the 2021 rally, AMC’s share price has undergone a series of heavy falls: the company’s stock declined about 85% in both 2022 and 2023, then a further 35% in 2024 and 61% in 2025 — cumulative losses exceeding 99% from the 2021 peak, according to recent reporting. Still, 2026 has offered a notable turnaround: through 4 September, the stock was up about 63% year-to-date.
What’s underpinning the recent interest?
There are a few concrete, measurable reasons investors and observers have become more upbeat about AMC this year:
- Stronger box-office results: summer ticket sales were reported up by about 26% compared with the prior year, surpassing recent seasonal norms.
- Improved earnings: AMC’s second-quarter results showed revenue of $1.6 billion, an increase of 14% year on year, and adjusted earnings in positive territory rather than a loss.
- Lower valuation metric: the company’s price-to-sales ratio was cited at about 0.28, below its five-year average of 0.31, suggesting analysts see some relative value on that multiple.
Those positives have to be weighed against several ongoing structural and financial concerns.
Risks that keep many cautious
Despite the improved top-line performance, the company still faces headwinds that make it a risky speculative play rather than a conventional blue-chip investment. Key issues flagged in recent analysis include:
- Heavy debt load — the business is carrying significant leverage from past capital needs.
- Share dilution — AMC has issued substantial additional equity, which reduces the economic interest of existing shareholders.
- Inconsistent profitability — while adjusted earnings were positive in the latest quarter, the company does not have a long track record of sustained profits and pays no dividend.
| Year | Reported share movement |
|---|---|
| 2021 | +>1,100%, peak above $600 |
| 2022 | -85% |
| 2023 | -85% |
| 2024 | -35% |
| 2025 | -61% |
| 2026 (YTD as of 4 Sep) | +63% |
Market capitalisation and scale
Despite the low per-share price, AMC remains a sizeable corporate entity. Recent reporting put its market value at roughly $2.4 billion, and the company’s box-office recovery has translated into meaningful revenue gains. Those facts help explain why some investors treat AMC differently from typical penny stocks, which are often speculative, early-stage companies without established revenue streams.
Nevertheless, analysts caution that other cinema operators may present cleaner balance sheets or lower valuations, so investors should compare peers before deciding. One commentator summarised the view by acknowledging the brighter revenue and seasonality benefits while still noting the balance-sheet and shareholder-value concerns.
For South African entertainment followers and investors watching global cinema trends, AMC’s story is a useful case study: it shows how a strong summer box-office cycle can improve operating metrics, yet it also underlines how past financing decisions and capital structure can limit how gains translate into shareholder returns. Readers keen on the stock were advised to dig deeper into the company’s financials and risk profile before committing capital; at least one analyst said they were inclined to pass rather than buy.
Overall, AMC’s rebound raises intriguing questions about theatre economics post-pandemic and whether improved attendance can sustainably offset debt and dilution pressures. It is a stock to watch — and to treat with caution.