Master Drilling Group reported a rise in revenue for the six months ended June 2026, but the drilling and mining services firm said tighter working capital, client-driven project delays and equipment availability constraints weighed on profit conversion and cash generation.
Top-line growth, limited cash conversion
Revenue for the period rose by 17% to $155.8 million, while operating profit held steady at $26.2 million. Profit after tax declined by 3.9% to $17.4 million, although headline earnings per share (HEPS) improved in dollar terms, rising 16.7% to 11.2 US cents. In rand terms the company said HEPS increased to 183.9 cents.
Despite top‑line gains, cash generated from operations was modest at $1.9 million. The group attributed the low operating cash flow largely to investment in working capital required to support the revenue increase.
Capital expenditure and fleet utilisation
Master Drilling spent $4.3 million on capital expenditure in the period. The company allocated 44% of that spend to expansion and 56% to maintaining its existing fleet, signalling a balance between growth and sustaining operational capability.
However, utilisation of key equipment was low: just 64% of raise‑boring rigs and 38% of slim‑drilling rigs were in use during the period. Low utilisation rates highlight spare capacity and the potential drag on margins and return on invested capital while rigs remain idle.
Order book and pipeline growth — but conversion remains key
The group’s order book expanded to $400.9 million from $305.6 million a year earlier, while the sales pipeline more than doubled to $1.06 billion from $515 million. The company cautioned that the pipeline must be converted into secured work for the pipeline to translate into earnings, noting that mobilisation and execution will determine cash realisation.
| Metric | H1 2026 |
|---|---|
| Revenue | $155.8m |
| Operating profit | $26.2m |
| Profit after tax | $17.4m |
| Cash from operations | $1.9m |
| Capex | $4.3m |
| Order book | $400.9m |
| Sales pipeline | $1.06bn |
Regional performance and execution risks
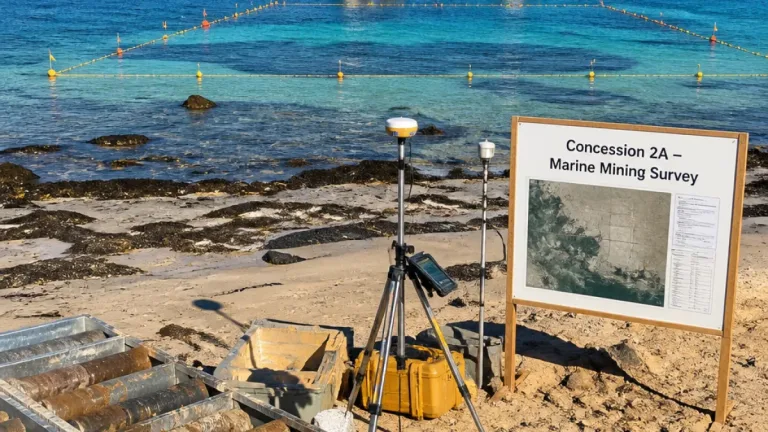
Operational performance was uneven across regions. In South America new drilling operations and equipment mobilisation for large shaft projects supported growth, although some projects were delayed after clients adjusted schedules. In Central and North America, heightened tender activity grew the pipeline, but client‑driven execution delays affected operations. Southern Africa recorded a slower start to the year, while other African operations benefited from contract wins, expanded scopes and the restart of previously paused work.
The group identified a range of risks that could influence future performance, including:
- geopolitical volatility;
- supply‑chain disruption and cost inflation;
- project timing and mobilisation challenges;
- equipment availability and utilisation constraints.
Master Drilling also said it is expanding beyond its traditional drilling services, but provided no additional financial detail on diversification in the update.
What this means for households and industry
For households and suppliers linked to mining services, Master Drilling’s results underline two immediate realities. First, top‑line growth does not automatically generate cash for wages, suppliers and reinvestment — working capital can consume free cash when projects ramp up. Second, under‑utilised equipment and project delays increase the risk of uneven employment demand across regions, which can affect contractors and local service providers.
The enlarged sales pipeline offers scope for future revenue and jobs, but conversion into secured contracts and reliable mobilisation will determine whether the promise translates into sustained cash flow. Investors and stakeholders will be watching whether the firm can turn its stronger order book into operating cash and higher returns in the second half of the year.
WE NEWS does not provide financial advice; readers should seek professional guidance before making investment decisions.