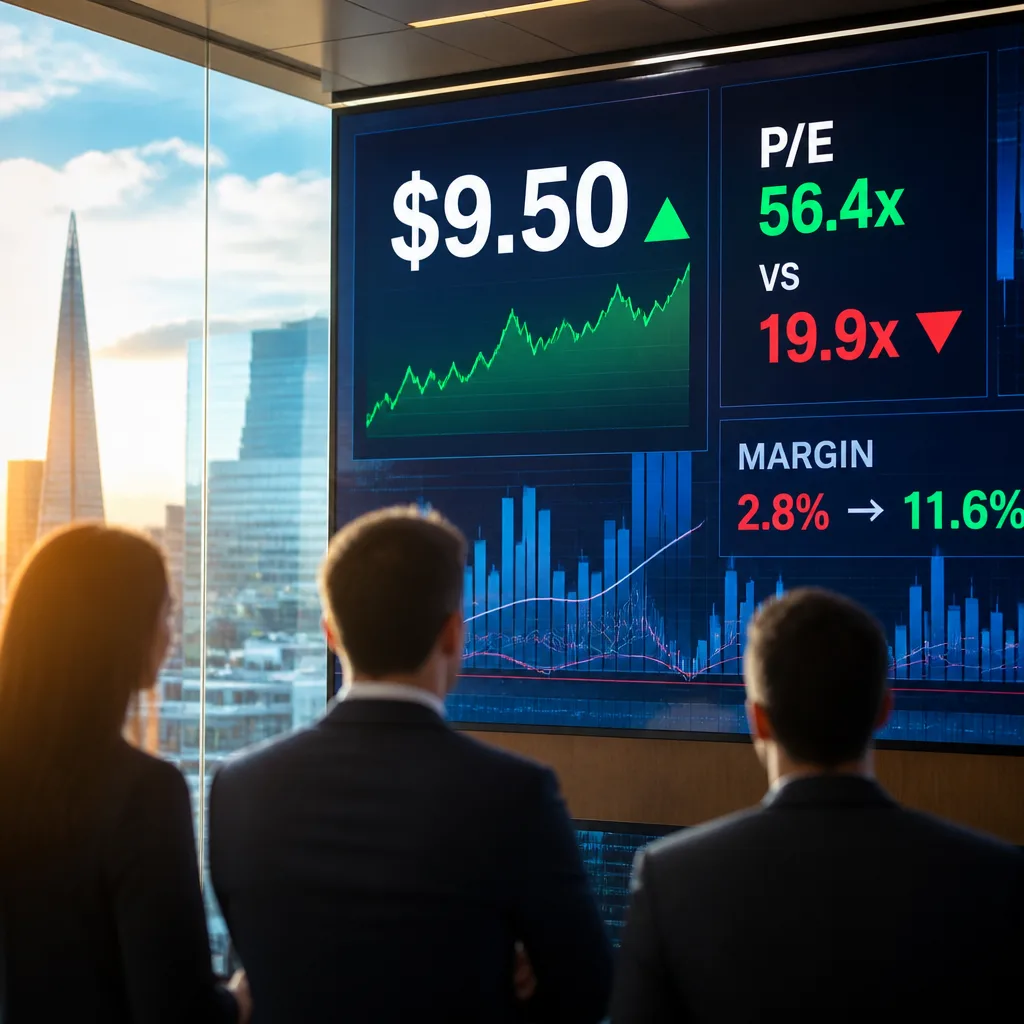
Global Business Travel Group closed at $9.50, a level that recent fair-value work also pegs as roughly correct — a conclusion that leaves little obvious upside for buyers and sets up a debate about whether the market has already priced in the company’s recovery.
Momentum but little margin for error
The stock has enjoyed a strong run: a year-to-date gain of 26.33%, a one-year total shareholder return of 16.71% and a three-year total return of 72.73%. Those figures suggest investor confidence has been steadily rebuilt after earlier setbacks. Yet that optimism sits alongside valuation measures that give a more cautious read.
Analysts producing one widely followed valuation view assume revenue growth of just 3.7% per year for the next three years, but expect profit margins to widen substantially — from 2.8% now to 11.6% in three years — to justify the current price. That combination of modest top-line progress and aggressive margin expansion is central to the argument that the current price is “about right”: a fair value of $9.50 matching the recent close.
High multiples expose the stock to disappointment
Viewed through earnings multiples, the stock appears richly priced. The shares trade on roughly 56.4x earnings, compared with about 19.9x for the wider US hospitality group. Even an internal fair-ratio assessment for the company sits at 47.7x, still below the current multiple. That gap means expectations baked into the share price are demanding: profits must rise materially or the multiple will have to compress.
| Metric | Value |
|---|---|
| Share close | $9.50 |
| Year-to-date return | 26.33% |
| 1-year TSR | 16.71% |
| 3-year TSR | 72.73% |
| Assumed revenue growth | 3.7% p.a. |
| Assumed margin expansion | 2.8% → 11.6% (3 years) |
| P/E (company) | 56.4x |
| P/E (sector) | 19.9x |
What the numbers mean for wages, prices and jobs
A valuation that depends on margin expansion rather than rapid revenue growth has practical implications. If management delivers productivity gains or cost cuts to hit the higher margins, that could constrain wage growth for administrative and support roles even as the company invests selectively in sales and technology. Conversely, stronger-than-expected corporate travel budgets — the central demand driver for the business — would lift revenues and make sustained pay rises and hiring more affordable.
For travellers and buyers of corporate travel services, a company under pressure to improve margins might prioritise higher-margin services or ancillary fees, which could feed through to the prices companies pay for travel management. For employees, the path to higher wages is likely to be slower if margin improvement relies on headcount rationalisation or efficiency targets rather than top-line expansion.
- Main upside catalysts: faster recovery in corporate travel budgets; successful integration and synergy realisation from acquisitions.
- Key downside risks: failure to expand margins as assumed; weaker-than-expected revenue growth; multiple compression towards peer levels.
Investors bullish on the stock point to recent double-digit shareholder returns and reported profit growth. Critics counter that the current price assumes significant improvement in profitability without demanding much revenue expansion. That tension explains why a fair value estimate can line up with the market price yet leave room for sharp re-rating in either direction if assumptions change.
Ultimately, the share price appears to be a referendum on whether the company can execute margin improvements while modestly growing sales. For markets sensitive to interest rates, travel budgets and macroeconomic cycles, that is a delicate balancing act — one that will determine whether the recent gains in share price translate into sustainable returns for investors, and whether staff and customers feel the effects in pay packets and bills.