A 36-year-old public servant in Guelph is working to rebuild her household finances and career after taking two extended parental leaves that coincided with rapid increases in living costs and constrained childcare access.
Returning to work amid mounting household debt
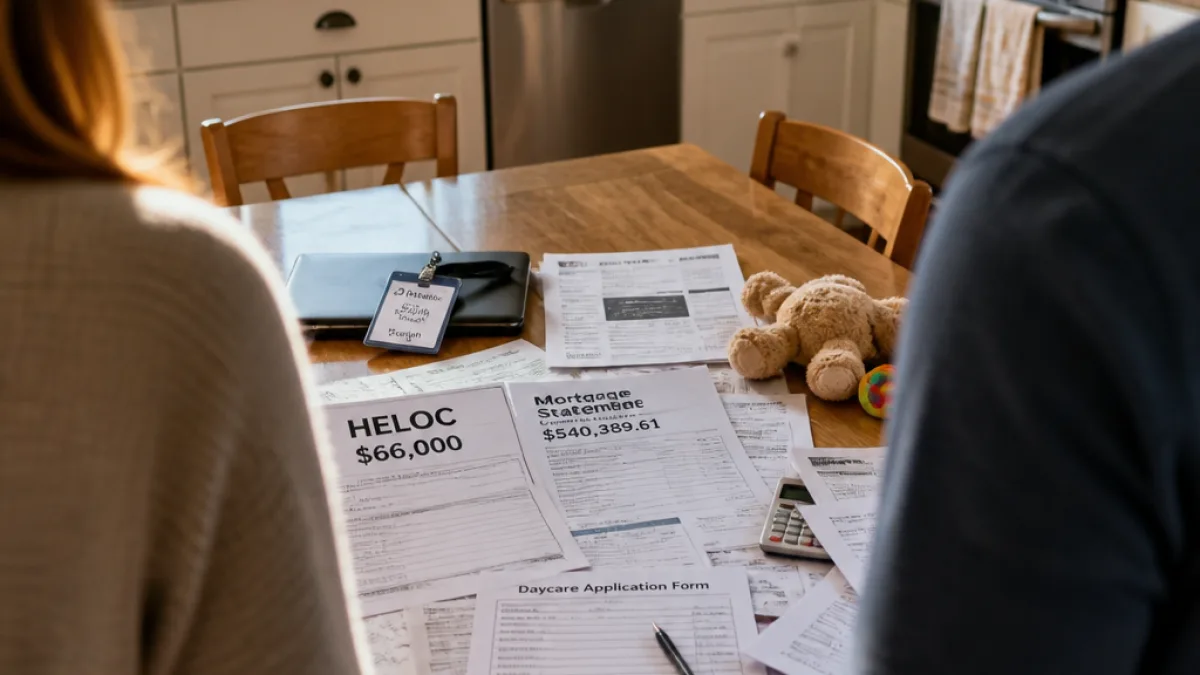
The woman, who asked to be identified only as Julia, earns about $107,000 annually from her provincial government job and receives $5,628 a year in Canada Child Benefit. Her partner, who works in hospitality, earns roughly $100,000 a year. Despite those incomes, the couple carried significant debt at the end of her most recent leave: $66,000 on a home equity line of credit and about $479,422 on their mortgage. Their reported savings include $8,100 in an RRSP and $23,084 in an RESP.
| Item | Amount |
|---|---|
| Annual employment income | $107,000 |
| Canada Child Benefit | $5,628 |
| HELOC balance | $66,000 |
| Mortgage balance | $479,422 |
| RRSP savings | $8,100 |
| RESP savings | $23,084 |
Parental leave lengths, childcare scarcity and compounding costs
Julia took 18 months for her first maternity leave and 16 months for her second. During that time she received a workplace top-up that ended in November 2025 and Employment Insurance benefits that ceased in April. Unable to secure a daycare placement that would have allowed an earlier return to paid work, the family turned to their line of credit to cover rising household costs.
- Two extended leaves: 18 months and 16 months
- Work top-up ended: November 2025
- EI benefits ended: April (year not specified in interview)
- Primary short-term coping: home equity line of credit
"It felt awful to do,"
Julia said using the line of credit was distressing despite her partner's support for taking time away from work. "We’ll never get this time back," she said, describing the decision to prioritise early caregiving despite the financial setback.
Local context: why this matters in Guelph
Guelph families juggling careers and caregiving face a mix of pressures familiar to many Ontario municipalities: high housing costs, rising everyday expenses and a limited supply of regulated childcare spots. For households like Julia's, extended leaves intersect with those pressures and can stall retirement and education saving plans while increasing reliance on credit.
Julia describes recurring episodes of acute anxiety about money: she experiences a significant "freakout" about finances roughly once a year. Her upbringing, in a middle-class household where money was a frequent source of stress, colours how she responds to the family's present situation.
Consequences and prospects
With both parents employed, the family expects to recover financially over time, but the path will involve managing sizeable mortgage and HELOC balances while rebuilding savings. The couple's case highlights several policy and community issues that affect Guelph residents more broadly:
- Availability of affordable, regulated childcare and its role in enabling earlier return to work.
- How parental leave top-ups and EI timing influence household cash flow.
- Impact of rising living costs on families who take extended caregiving leave.
As Guelph continues to grow and housing prices remain a dominant local concern, stories like Julia's underscore the trade-offs families make between caregiving and financial security. For many, the decision to take extended time with young children carries long-term implications for household debt, retirement savings and emotional well-being.
Local supports, municipal childcare planning and employer leave policies will shape how more families weather similar challenges in the years ahead. For now, Julia and her partner are focused on steady income, reducing reliance on credit and rebuilding their financial cushion after a period of concentrated caregiving.