Health savings accounts — when used as long-term investment vehicles rather than current-year spending accounts — can offer retirees a rare combination of tax benefits that make them powerful tools for covering medical expenses in retirement.
Why HSAs matter for retirement health costs
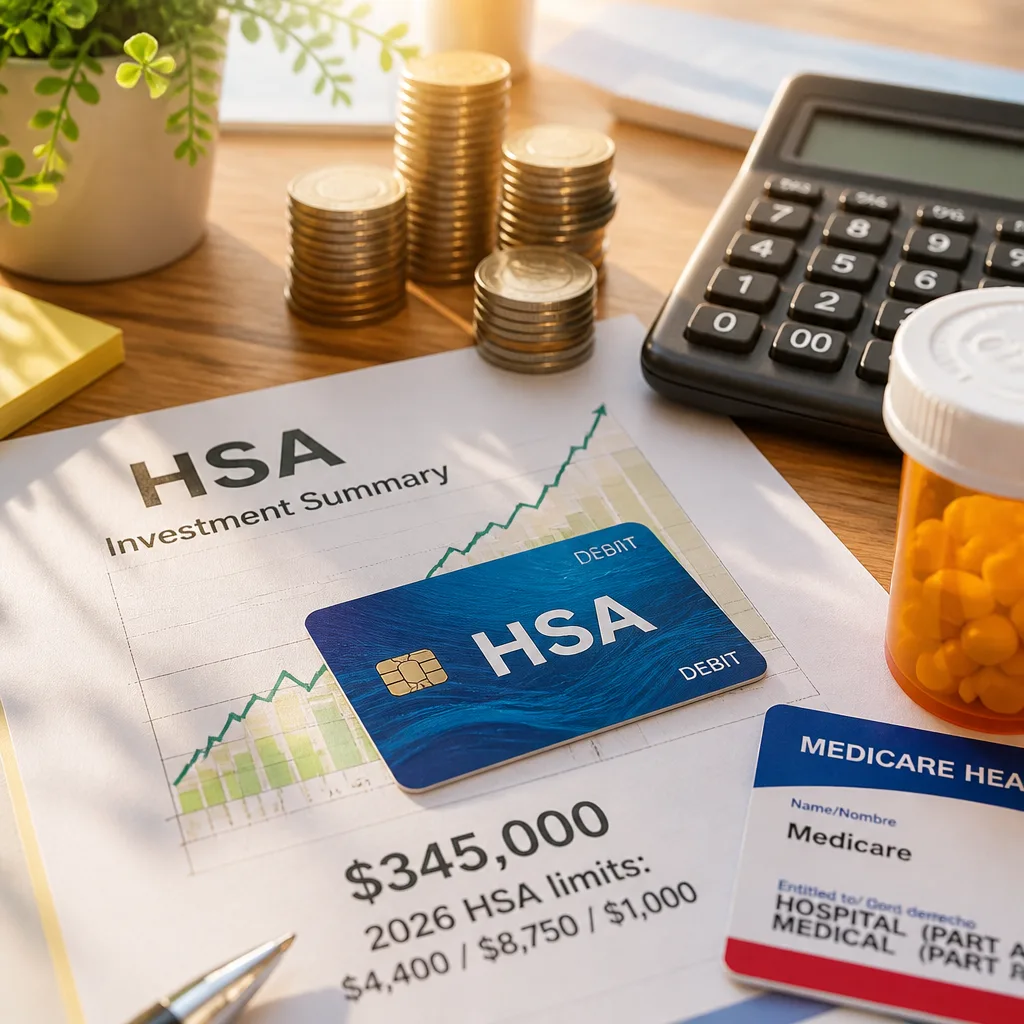
Financial- and health-planning estimates show medical expenses can consume a substantial share of retirement savings. A recent industry estimate puts lifetime medical costs for a 65-year-old couple at roughly $345,000 after tax; for an individual the figure is about $172,500. When planners factor in additional items such as long-term care and the Medicare IRMAA surcharges that can be triggered by large 401(k) distributions, the planning figure for a couple rises to about $410,000 over a 25-year retirement horizon.
HSAs are structured to help meet precisely those kinds of expenses. Contributions are federally deductible when made through payroll, account growth is tax-free, and qualified medical withdrawals are never taxed — regardless of age.
How the tax math compares
The three-way tax advantage sets HSAs apart from traditional retirement accounts:
- Contributions reduce taxable income when funded through payroll.
- Investment growth compounds tax-free inside the account.
- Qualified medical withdrawals are tax-free, even after Medicare enrollment.
That combination is particularly valuable at Medicare enrollment, when many health-related costs — including Part B and D premiums and certain out-of-pocket expenses — can be paid from the HSA without generating taxable income.
Contribution limits and catch-up strategy
The HSA contribution rules for 2026 provide meaningful capacity for pre-retirees to build a dedicated health fund:
| Category | 2026 Limit |
|---|---|
| Self-only coverage | $4,400 |
| Family coverage | $8,750 |
| Catch-up (age 55+) | $1,000 |
For married couples in which both spouses are 55 or older and each maintains a separate HSA, the combined annual deposit capacity rises to $10,750 — and every dollar contributed is deducted federally and is exempt from Social Security and Medicare payroll tax when done through payroll.
How to use the account effectively
Many account holders treat HSAs as convenient depositories for copays and current health expenses, withdrawing funds before they can grow. That approach sacrifices the account’s long-term tax advantages. A different approach is to:
- Fully fund the HSA each year up to the limit, including catch-up contributions when eligible.
- Invest HSA balances rather than keeping them in cash, allowing tax-free compounding over time.
- Reserve the HSA for qualified medical costs in later retirement years, using other assets for nonmedical spending earlier if needed.
Because qualified medical withdrawals remain tax-free after Medicare enrollment, retirees can use the account to pay premiums, dental, vision and hearing expenses, and certain long-term care premiums without creating taxable income. For example, a retiree withdrawing $15,000 annually from an HSA for those costs would not report that money on Form 1040.
What this means for retirement planning
HSAs are not a substitute for a diversified retirement plan, but they are a distinctive and underused tool for the specific and often large category of health-related retirement costs. Savers approaching retirement should review eligibility for a high-deductible health plan, evaluate their ability to fund an HSA, and consider treating the account as a tax-advantaged medical savings vehicle — especially in the decade before Medicare.
Financial advisers and plan sponsors who want to help clients make the most of HSAs should emphasize funding discipline, investment options inside the HSA, and the advantages of delaying medical withdrawals to later life when the tax-free benefit is most valuable.