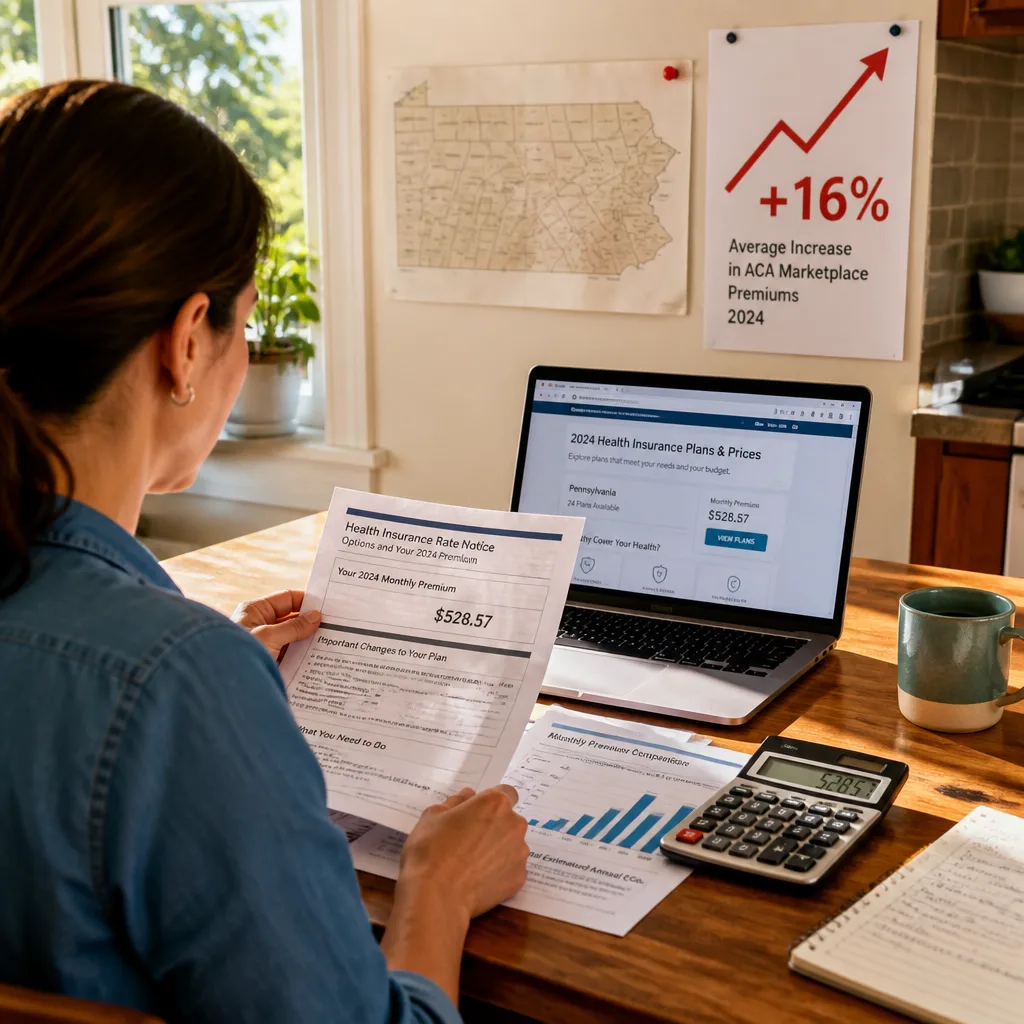
Pennsylvania consumers who buy health coverage through the Affordable Care Act marketplace can expect a substantial increase in premiums next year, the Pennsylvania Insurance Department said Monday. Insurers’ proposed rate filings indicate a near 16% rise for individuals who purchase their own plans and just over 10% for small businesses, according to the department.
State officials point to higher costs, federal policy changes
The department said health plans are required to submit proposed rates reflecting anticipated spending on medical care, prescriptions and other health costs. In its summary of filings, the department identified broad trends pushing premiums upward, including rising medical and prescription drug costs and greater overall utilization of services.
Officials also linked the increases in part to federal policy changes. After Congress did not reauthorize enhanced premium tax credits for 2026 and beyond, the department said, some people dropped marketplace coverage. That shift, the department warned, has placed additional pressure on medical providers by increasing uncompensated care, a dynamic that can contribute to higher insurer costs and higher premiums for those who remain enrolled.
“Unfortunately, health care cuts by the federal government continue to drive up costs for Pennsylvania families. We understand that these rate increases are rough on Pennsylvania families and businesses, and we fought insurers for every savings we could reasonably assert,”
The statement came from Pennsylvania Insurance Commissioner Michael Humphreys, who emphasized the department’s review efforts to limit increases where possible.
Options for consumers
The department encouraged residents to shop the state’s marketplace, Pennie, where eligible consumers can compare plans and determine whether they qualify for financial help. The filing summary reiterated that plans sold through Pennie continue to provide key consumer protections, including coverage for preexisting conditions and essential health benefits such as preventive care, prescription drugs and hospital services.
- Consumer protections: Coverage for preexisting conditions and essential benefits.
- Plan choices: Multiple metal tiers (bronze, silver, gold, platinum) and network types (HMO, EPO, PPO).
- Financial help: Pennie lists available financial assistance for those who qualify.
The department also reminded consumers that open enrollment for the marketplace typically runs from Nov. 1 through Dec. 15, giving people a window to review options and seek subsidies if eligible.
What the filings show
The department’s summary released Monday did not provide an itemized list of every carrier’s request but gave the statewide averages consumer advocates and employers will likely use to anticipate next year’s market. The department attributes the statewide average increases to a combination of rising health care costs and enrollment shifts following the lapse of enhanced tax credits.
| Market segment | Proposed average increase |
|---|---|
| Individual marketplace | Nearly 16% |
| Small-group (small businesses) | More than 10% |
How much of the requested increases become final will depend on the department’s regulatory review. State regulators examine insurer filings to verify cost assumptions and to determine whether requested rates are justified before approving or modifying them.
For many households already budgeting tightly, even a modest jump in premiums can alter choices about coverage or out-of-pocket spending. The department urged consumers to compare plans on Pennie and to explore subsidy eligibility, particularly given the range of plan tiers and network arrangements that affect both monthly premiums and potential medical bills.
Insurers cited in the filing process typically provide their own detailed rationales for rate changes in their submissions to the state, including projections for utilization, drug spending and provider costs. The department said it contested increases where possible during its review.
The rate filings add to a broader national conversation about health coverage affordability following recent shifts in federal subsidy policy. State regulators and consumer advocates are likely to watch how the final approved rates compare with these initial insurer requests and what consumer assistance efforts — from plan shopping tools to state-based outreach — might blunt the immediate financial impact on families and small employers.