ORANGE — Orange County officials are confronting a renewed debate over who should hold investment authority after a recent move to shift that power away from the elected Treasurer-Tax Collector coincided with purchases of long-term bonds that have declined in value as interest rates rose.
Background and the mark-to-market requirement
The county must report investments at market value under Governmental Accounting Standards Board Pronouncement 31, adopted nationally in March 1997 in the wake of Orange County's 1994 Chapter 9 bankruptcy. That requirement — commonly called GASB 31 or "marking to market" — obliges municipalities to disclose the fair market value of cash equivalents and bonds on financial statements.
Supporters of marking to market have long argued it prevents the concealment of unrealized losses by forcing disclosure when interest rates change. That debate was a central issue in the 1994 county treasurer's race between Robert L. "Bob" Citron and John Moorlach. At the time, The Wall Street Journal quoted Citron saying,
"I can hold to maturity,"and Moorlach countered that investments should be marked to market like mutual funds and other institutional investors.
Recent decisions and results
According to local commentary, the county chief executive persuaded the Board of Supervisors to transfer investment authority from the elected Treasurer-Tax Collector. The new arrangement placed a recently hired chief financial officer, described in the commentary as unqualified and inexperienced, in charge of the portfolio.
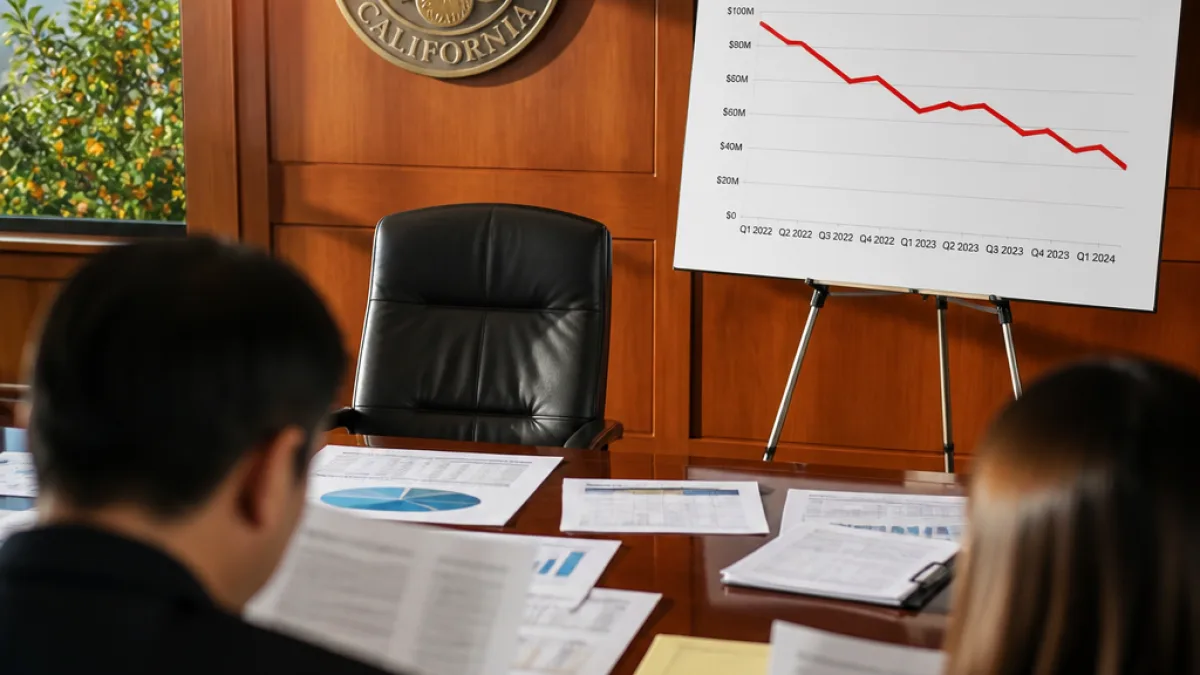
During the first six months of this year, the county reportedly increased purchases of long-term bonds under the assumption that interest rates would decline. Instead, rates moved higher. The result: a portfolio that was down about $50 million on those recent acquisitions as of the end of April.
- Policy change: Investment authority removed from elected Treasurer-Tax Collector.
- Strategy: Significant purchases of long-term bonds in early 2026.
- Current exposure: About $50 million in unrealized losses reported at the end of April.
Disclosure and timing
Because GASB 31 requires disclosure of market value, the county faces a fiscal-year-end accounting point: its fiscal year closes June 30, 2026. That timing will determine how the mark-to-market losses are reflected in official financial statements and budgets.
Critics cited in the commentary argue the shift of authority and the timing of the bond purchases echo earlier mistakes in county investment governance and risk management. Some commentators have urged the Board to restore investment authority to the elected Treasurer-Tax Collector, citing long-term experience and a conservative approach to investing county funds.
| Item | Date / Period |
|---|---|
| Orange County Chapter 9 bankruptcy | 1994 |
| GASB 31 adoption (mark to market) | March 1997 |
| Recent bond purchases | First six months of 2026 |
| Reported unrealized losses on recent acquisitions | About $50 million (end of April 2026) |
| County fiscal year end | June 30, 2026 |
The commentary invoked the 1994 episode as cautionary precedent and warned that placing investment decisions with an inexperienced financial officer while moving authority from the elected treasurer could repeat past missteps.
"Mutual funds and everyone else marks to market, and if I'm county treasurer, I will mark investments to market," the commentary recalled John Moorlach saying during the 1994 campaign. "Not marking to market is just a way of concealing losses," it added.
Local officials have not yet released a full public accounting tied to the fiscal year close. How the county presents those market valuations in its June 30 financial statements will determine whether the $50 million figure remains as a reported unrealized loss, is mitigated by subsequent market movements, or prompts policy action by the Board of Supervisors.
For Orange residents, the issue raises immediate questions about oversight, the role of elected fiduciaries versus appointed staff, and how investment strategy and disclosure will affect the county's fiscal transparency going forward.