The global market for so-called lifestyle drugs — treatments aimed at improving quality of life rather than curing acute illness — is expected to expand steadily through 2035, according to a new IndexBox forecast. The report paints a picture of a sector reshaped by demography, technology and evolving consumer demand.
What the forecast says
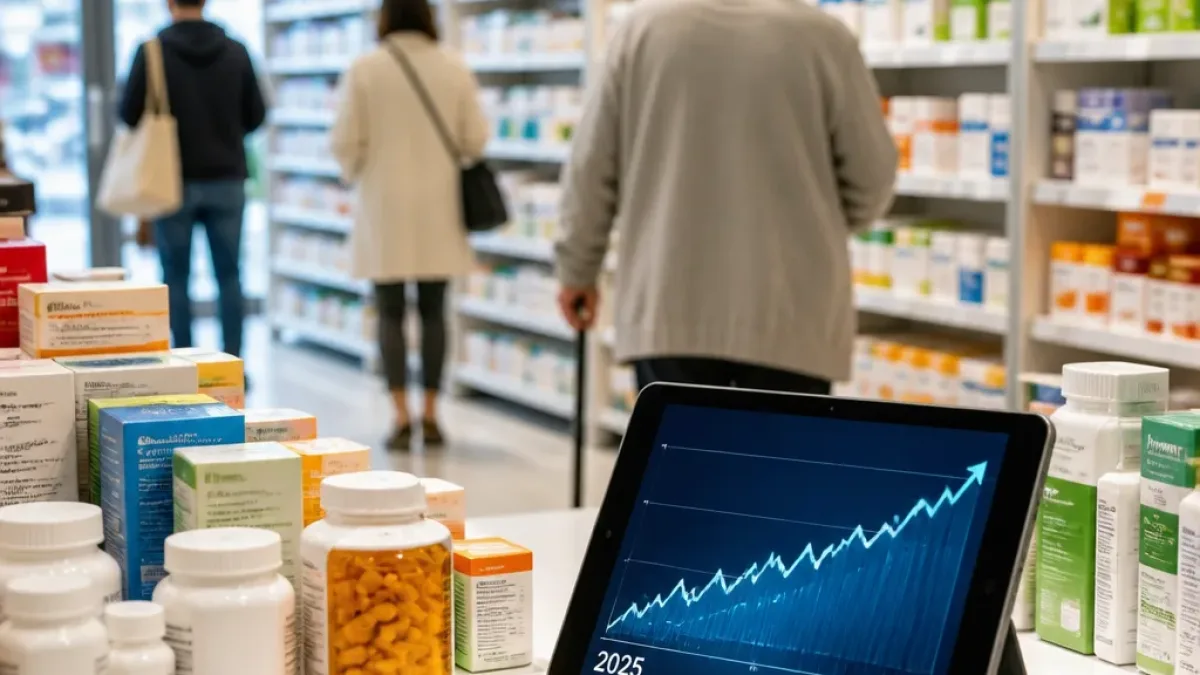
IndexBox’s baseline scenario projects a compound annual growth rate of 6.8% across the 2026–2035 period, with a market index rising to 193.4 by 2035 (with 2025 set to 100). The analysis describes a market that is becoming more segmented, more technologically integrated and subject to increasing regulatory scrutiny.
| Metric | Value |
|---|---|
| Projected CAGR (2026–2035) | 6.8% |
| Market index in 2035 (2025=100) | 193.4 |
Drivers and dynamics
The forecast links growth to several overlapping forces. Chief among them are demographic trends — notably the ageing of populations in many developed countries — and rising disposable incomes in middle-income markets. Consumers are increasingly treating health and wellness as discretionary spending, and the fusion of medical science with direct-to-consumer marketing and digital health platforms has widened access to and awareness of these products.
IndexBox also highlights supply-side shifts. The market is moving toward a more regionally diversified supply architecture and more disciplined procurement practices among buyers. Companies that can demonstrate strong safety and clinical profiles, while building trusted consumer brands, are likely to capture disproportionate value.
Implications for consumers and policy
For consumers, the forecast suggests broader availability of treatments that target non-life-threatening conditions and lifestyle preferences. That can mean more options, greater convenience and potentially more direct-to-consumer offerings delivered through telehealth and e-commerce. However, the report also signals heightened regulatory attention — a reminder that increased choice may bring greater scrutiny over safety, marketing claims and affordability.
Policymakers and health systems may face trade-offs. On the one hand, products that improve quality of life can reduce the burden of chronic conditions and support ageing in place. On the other, broader uptake of lifestyle drugs could amplify concerns about out-of-pocket costs, equitable access and the need for robust post-market surveillance.
- Consumers: Expect more options and direct-to-consumer channels, but also a need to scrutinize claims and safety information.
- Industry: Winners will be those who combine credible clinical evidence with trusted branding and regional supply resilience.
- Policymakers: Must balance innovation and access with oversight to ensure safety and affordability.
What to watch next
The IndexBox outlook recommends watching several areas closely: regulatory shifts that affect approval and marketing of lifestyle treatments; technological integration, especially digital health platforms that change how products reach consumers; and regional demand patterns as middle-income markets mature.
For Canadians, these trends could influence which treatments become available domestically and how they are paid for — whether through private insurance, public coverage discussions, or out-of-pocket spending. Consumers interested in lifestyle treatments should prioritise products backed by solid clinical evidence, verify regulatory approvals, and consult health professionals about risks and benefits.
As the market matures, clarity around safety, pricing and access will matter as much as the new products themselves. For now, the forecast suggests steady growth rather than a sudden boom — a slowly accelerating wave that will require attention from consumers, industry and regulators alike.